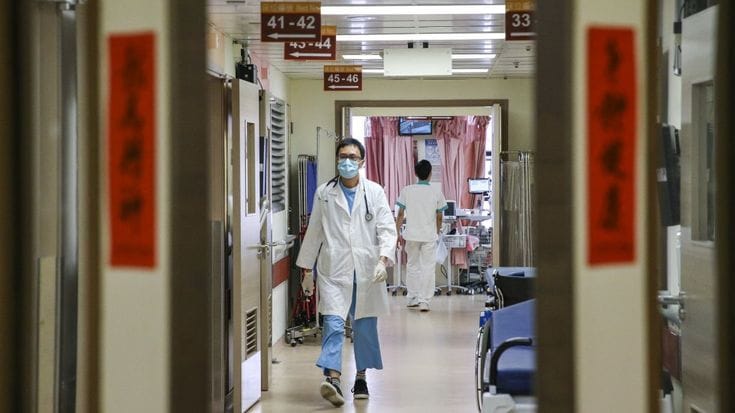
Secretary for Health Lo Chung-mau tabled the Healthcare Financing and Universal Coverage Reform Bill in the Legislative Council on Wednesday, a 248-clause piece of legislation that represents the most comprehensive reform of Hong Kong's healthcare financing system since the introduction of the Hospital Authority in 1990. The bill proposes a mandatory health insurance scheme, a substantially expanded electronic health record system, new regulations governing private healthcare pricing transparency, and a structural framework for public-private partnership in specialist care delivery.
The Case for Reform
Hong Kong's two-tier healthcare system, with a heavily subsidised public sector funded primarily from general taxation and a well-developed private sector serving insured and affluent patients, has delivered impressive population health outcomes at relatively modest cost, with life expectancy at 84 years among the highest in the world. However, the system faces structural sustainability challenges as the population ages and the burden of chronic disease increases.
Public hospital waiting times for non-urgent specialist consultations, which averaged 82 weeks in 2025, represent the system's most visible failure point, creating health risks and economic costs as patients with conditions treatable in early stages deteriorate while awaiting specialist review. The bill's public-private partnership framework directly addresses this bottleneck by allowing the Hospital Authority to purchase specialist consultation capacity from private hospitals and clinics under negotiated service agreements, redirecting patients from public waiting lists to private facilities with costs covered by the expanded subsidised scheme.
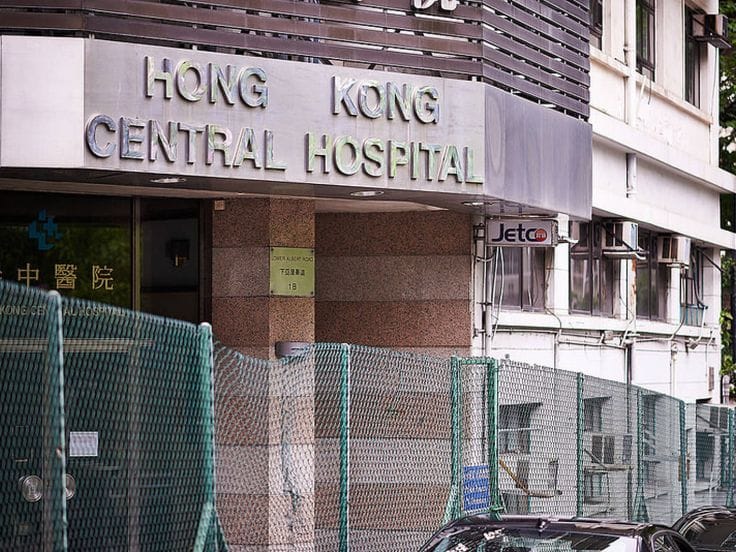
The Healthcare Reform Bill addresses 82-week public hospital specialist waiting times through expanded public-private partnerships and a mandatory insurance scheme.
The Mandatory Insurance Scheme
The most politically significant component of the bill is the mandatory health insurance provision, which requires all Hong Kong residents with monthly income above HK$15,000 to enrol in a certified health insurance plan meeting minimum coverage standards. Employers of more than 20 employees will be required to provide health insurance as an employment benefit, with a government subsidy for lower-income workers and self-employed individuals to maintain affordability.
The mandatory scheme builds on and significantly expands the existing Voluntary Health Insurance Scheme, which currently covers approximately 1.2 million residents. Under the mandatory framework, an estimated additional 2.4 million residents would come under certified health insurance coverage, creating a substantially larger insured pool and enabling more efficient risk pooling across the population.
Electronic Health Record Expansion
The bill mandates universal participation in the Electronic Health Record system by all healthcare providers, public and private, within 36 months of the ordinance's enactment. Currently, the eHealth record system covers approximately 68 percent of Hong Kong residents and is used by the Hospital Authority and participating private practitioners, but significant gaps remain in private specialist and allied health records.
The bill mandates universal participation in the eHealth Record system within 36 months, covering all public and private healthcare providers.
Political Dimensions and Opposition
The bill has generated the most extensive pre-legislative public engagement of any piece of legislation in the current term, with the Health Bureau conducting 18 public consultations, 24 professional stakeholder forums and three rounds of written consultation that together attracted over 28,000 substantive responses. The medical profession, through the Medical Council and the Hong Kong Medical Association, has expressed broad support for the reform direction while raising technical concerns about specific provisions governing private practitioner participation requirements and fee schedule negotiations.
The insurance industry has welcomed the mandatory coverage requirement while seeking amendments to the certification criteria for qualifying health insurance products, arguing that the current minimum benefit specifications unduly constrain product design and may drive premiums above the levels affordable by middle-income households without government subsidy. The Secretary for Health has indicated willingness to engage on these technical details in the Bills Committee process.